Level 1, 206 Adelaide Terrace, Perth WA 6004
230 Railway Parade, Cannington WA 6107
 Best Accountant Perth | Accounting Firms in PerthBest Accountant Perth | Accounting Firms in Perth
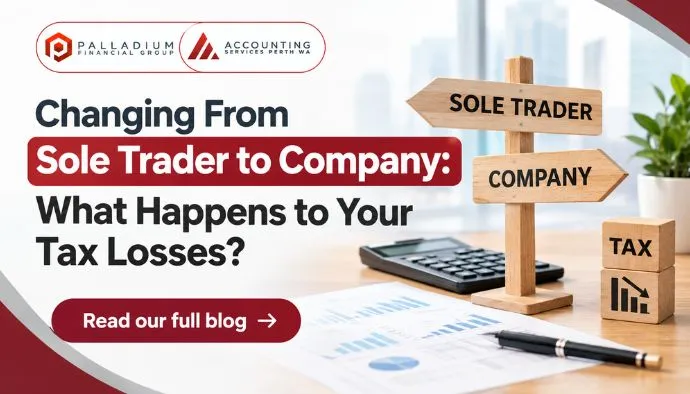
Moving your Australian business into a company can affect how past losses are treated. If your sole trader business has operated at a loss, one question matters before you make the switch: can the new company use that loss to reduce its future tax bill?
Usually, it cannot. The reason is that you and your company are treated as separate taxpayers.
As a sole trader, you report your business results through your personal tax return. After incorporation, the company reports its own income and expenses.
Changing the structure does not move your previous tax history into the new entity.
Imagine you operated a graphic design business as a sole trader and have $12,000 in eligible losses from an earlier year. You incorporate and continue working with the same customers. Your company cannot automatically deduct that $12,000 from its profits because the loss arose under your individual tax affairs.
Whether you can use the old loss against eligible personal income depends on the rules that apply to your circumstances.
Yes. Your company may be able to carry forward losses it incurs itself and use them against eligible profits in later years.
However, claiming these losses is subject to company tax rules. Depending on the circumstances, requirements involving ownership continuity or business continuity may apply.
Personal losses and company losses must therefore be recorded separately. Continuing the same business activities does not make the two interchangeable.
Incorporation may involve transferring business equipment, vehicles, goodwill or other property into the company. Such transfers can have consequences involving capital gains tax, GST or depreciation adjustments.
Some qualifying restructures may receive tax relief, but this depends on the relevant conditions. A concession affecting an asset transfer does not, by itself, make personal losses available to the company.
You should also arrange the company’s registrations and financial records correctly, including its own ABN and applicable tax registrations.
Start by reviewing your previous tax returns and identifying whether your losses are ordinary business losses, capital losses or amounts subject to special restrictions.
Then assess the proposed transfer and the obligations that will apply to the company. Professional tax planning and consulting can help you understand the likely tax consequences before the restructure takes place. Accurate business accounting also helps keep the financial records of both entities distinct.
Also read: 20 Tax Deductions Australians Can Claim in 2026: A Complete ATO Guide
Incorporating your business does not usually allow you to transfer personal tax losses to a company. Your existing losses must be assessed under individual tax rules, while the company must meet the requirements for claiming its own losses. Before restructuring, seek professional advice to understand the tax implications and keep both entities’ financial records accurate. Accounting services can help you manage the transition and maintain clear financial records as your business grows.
Generally, no. Tax losses incurred as a sole trader belong to you as an individual and cannot automatically be transferred to your newly established company. The company must calculate and claim its own eligible losses under Australian tax rules.
Your existing losses may remain available under the individual tax rules, depending on their type and your circumstances. Incorporating your business does not automatically cancel eligible losses, but it does not make them available to the company either.
Yes. An Australian company may carry forward eligible tax losses to offset future taxable income, provided it satisfies the applicable requirements, including relevant ownership or business continuity tests where required.
Potentially. Transferring business assets may trigger capital gains tax, GST or depreciation adjustments, depending on the transaction. Certain concessions may apply if the eligibility conditions are met, so professional tax advice is recommended before transferring assets.
Yes. A tax professional can review your existing losses, assess asset transfer implications and explain the company’s ongoing tax obligations. Careful planning can help you avoid unexpected costs and establish accurate financial records.